Every government scheme runs on rules — and the Wazir-e-Azam Apna Ghar Program 2026 is no exception. Understanding the Apna Ghar Program rules and conditions before you apply protects you from surprises, rejected applications, and penalties later. In this complete guide, we explain the eligibility rules, loan terms and conditions, property rules, your obligations as a borrower, what happens if rules are broken, and answers to frequently asked questions.
Why the Rules and Conditions Matter
The program offers subsidized financing — fixed 5% markup, up to Rs. 10 million, 20-year tenure — and in return it sets clear conditions on who can borrow, what can be financed, and how the loan must be used. Knowing these upfront keeps your application smooth. For the applicant-side summary, see our eligibility guide.
Eligibility Rules
Pakistani Citizenship
You must be a Pakistani citizen holding a valid CNIC (or NICOP for overseas Pakistanis).
First-Time Homeowner Priority
The program prioritizes applicants who do not already own residential property — see the first-time homeowners guide.
Age Limits
Applicants must be 18+ (some banks require 21+), and the loan must be fully repaid by age 60–65 — see the age limit guide.
Verifiable Income
Salaried or self-employed applicants need 2–3 years of verifiable income — see income proof documents.
Excluded Applicants
Employees of banks, DFIs and microfinance banks are barred from the program under SBP’s September 2026 circular.
Loan Rules and Conditions
| Condition | Rule |
|---|---|
| Maximum financing | Up to Rs. 10 million |
| Financing ratio | Up to 90% of property value (10% down payment) |
| Markup rate | Fixed 5% per annum for the first 10 years (see markup guide) |
| Tenure | 5 to 20 years |
| Processing fee | No processing fee charged |
| Early repayment | No prepayment penalty |
| Use of funds | Strictly for residential purposes — house purchase, construction, flat, or renovation |
Property Rules
- Only residential properties qualify — commercial-only properties are excluded (see property requirements).
- The property must pass property verification — clear title, no disputes, approved plans.
- The property must be for your own residence, not as a rental investment.
- Size limits apply: urban houses up to 5 marla, rural up to 10 marla, flats up to 1,500 sq ft.
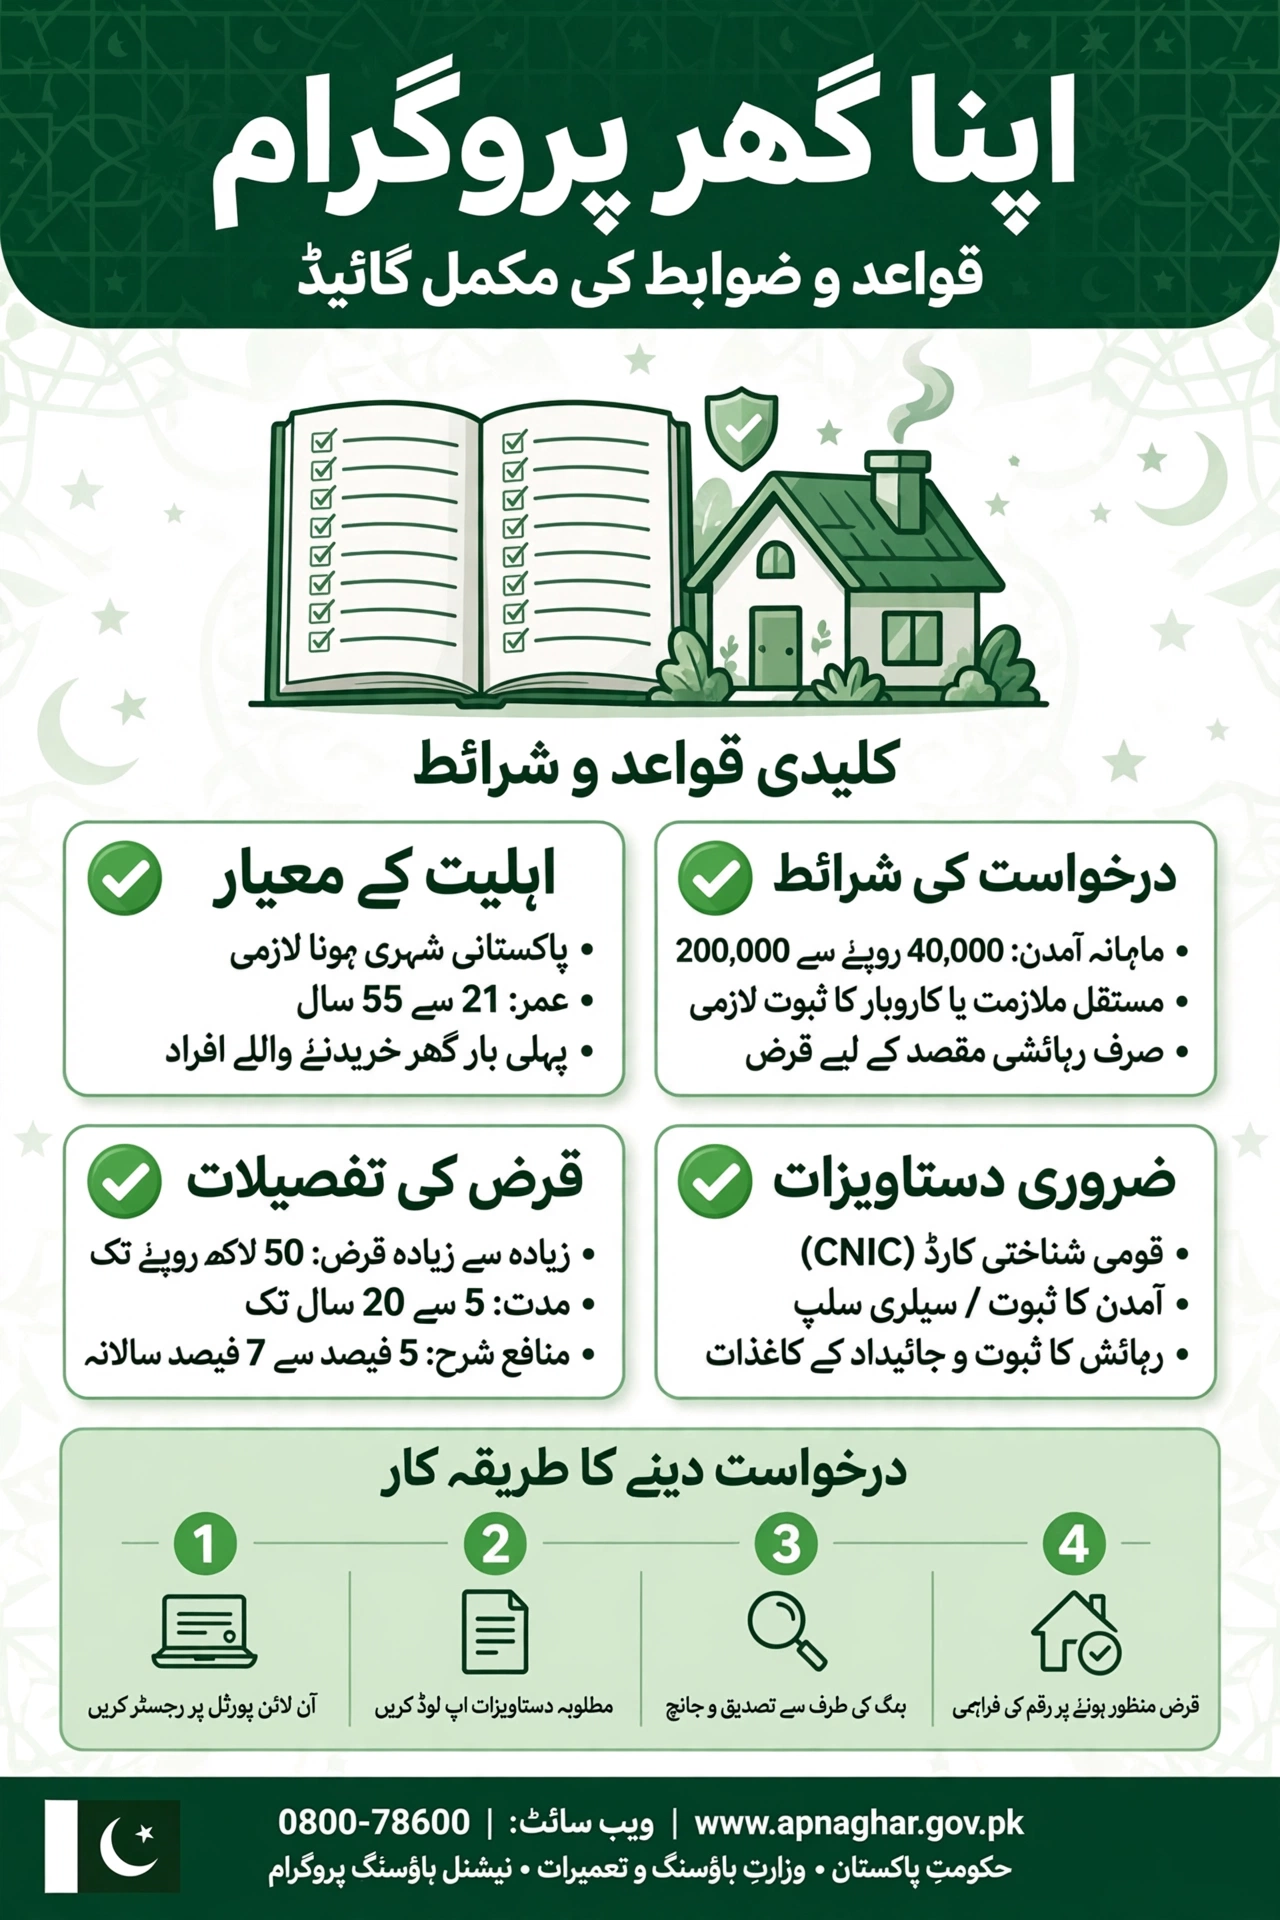
Borrower Obligations
- Timely installments: pay every monthly installment on time — defaults damage your credit record and can trigger recovery.
- Accurate information: all documents and declarations must be genuine; fraud leads to cancellation and legal action.
- Inform the bank of changes: update your mobile number and address if they change.
- Maintain the property: the financed property serves as security — keep it insured and in good condition as required.
- No unauthorized sale: you cannot sell or transfer the property without the bank’s written consent until the loan is cleared.
What Happens If You Break the Rules?
- Late payments: late-payment charges apply and your credit history suffers.
- False information: the application is cancelled, disbursed amounts can be recalled, and legal proceedings may follow.
- Misuse of funds: using the loan for non-residential purposes violates the agreement and can lead to immediate recall.
- Default: persistent default allows the bank to enforce its security — including sale of the mortgaged property.
Avoid these outcomes with our pre-submission checklist.
FAQs – Apna Ghar Program Rules and Conditions
What is the most important rule of the program?
The financing is strictly for your own residential use — it cannot be used for commercial property or investment flipping.
Can I sell the property before repaying the loan?
Only with the bank’s written consent; the property is mortgaged as security until the loan is fully repaid.
Is there any processing fee?
No — the program charges no processing fee, and there is no penalty for early repayment.
Can bank employees apply?
No — SBP’s September 2026 circular bars employees of banks, DFIs and microfinance banks from the program.
What if I miss an installment?
Late-payment charges apply and your credit record is affected; contact your bank immediately if you face difficulty.
Can I rent out the financed house?
The program is for owner-occupied housing — renting it out violates the spirit and terms of the agreement.
Where can I read the official terms?
Always rely on the official portal and your bank’s sanction letter — never on agents or forwarded messages. For help, see the helpline guide.
Final Thoughts
The Apna Ghar Program rules and conditions are designed to keep subsidized housing finance fair: genuine applicants, genuine homes, honest repayment. Follow them, and the program’s benefits — 5% markup, 10% down payment, 20-year tenure — are fully yours.