Why is everyone talking about the Wazir-e-Azam Apna Ghar Program 2026? Because its benefits make home ownership possible for families who could never afford a conventional mortgage. In this guide, we explain the Apna Ghar Program benefits and key features one by one — subsidized markup, low down payment, long tenure, and more — plus who benefits most, a comparison with ordinary home loans, and answers to frequently asked questions.
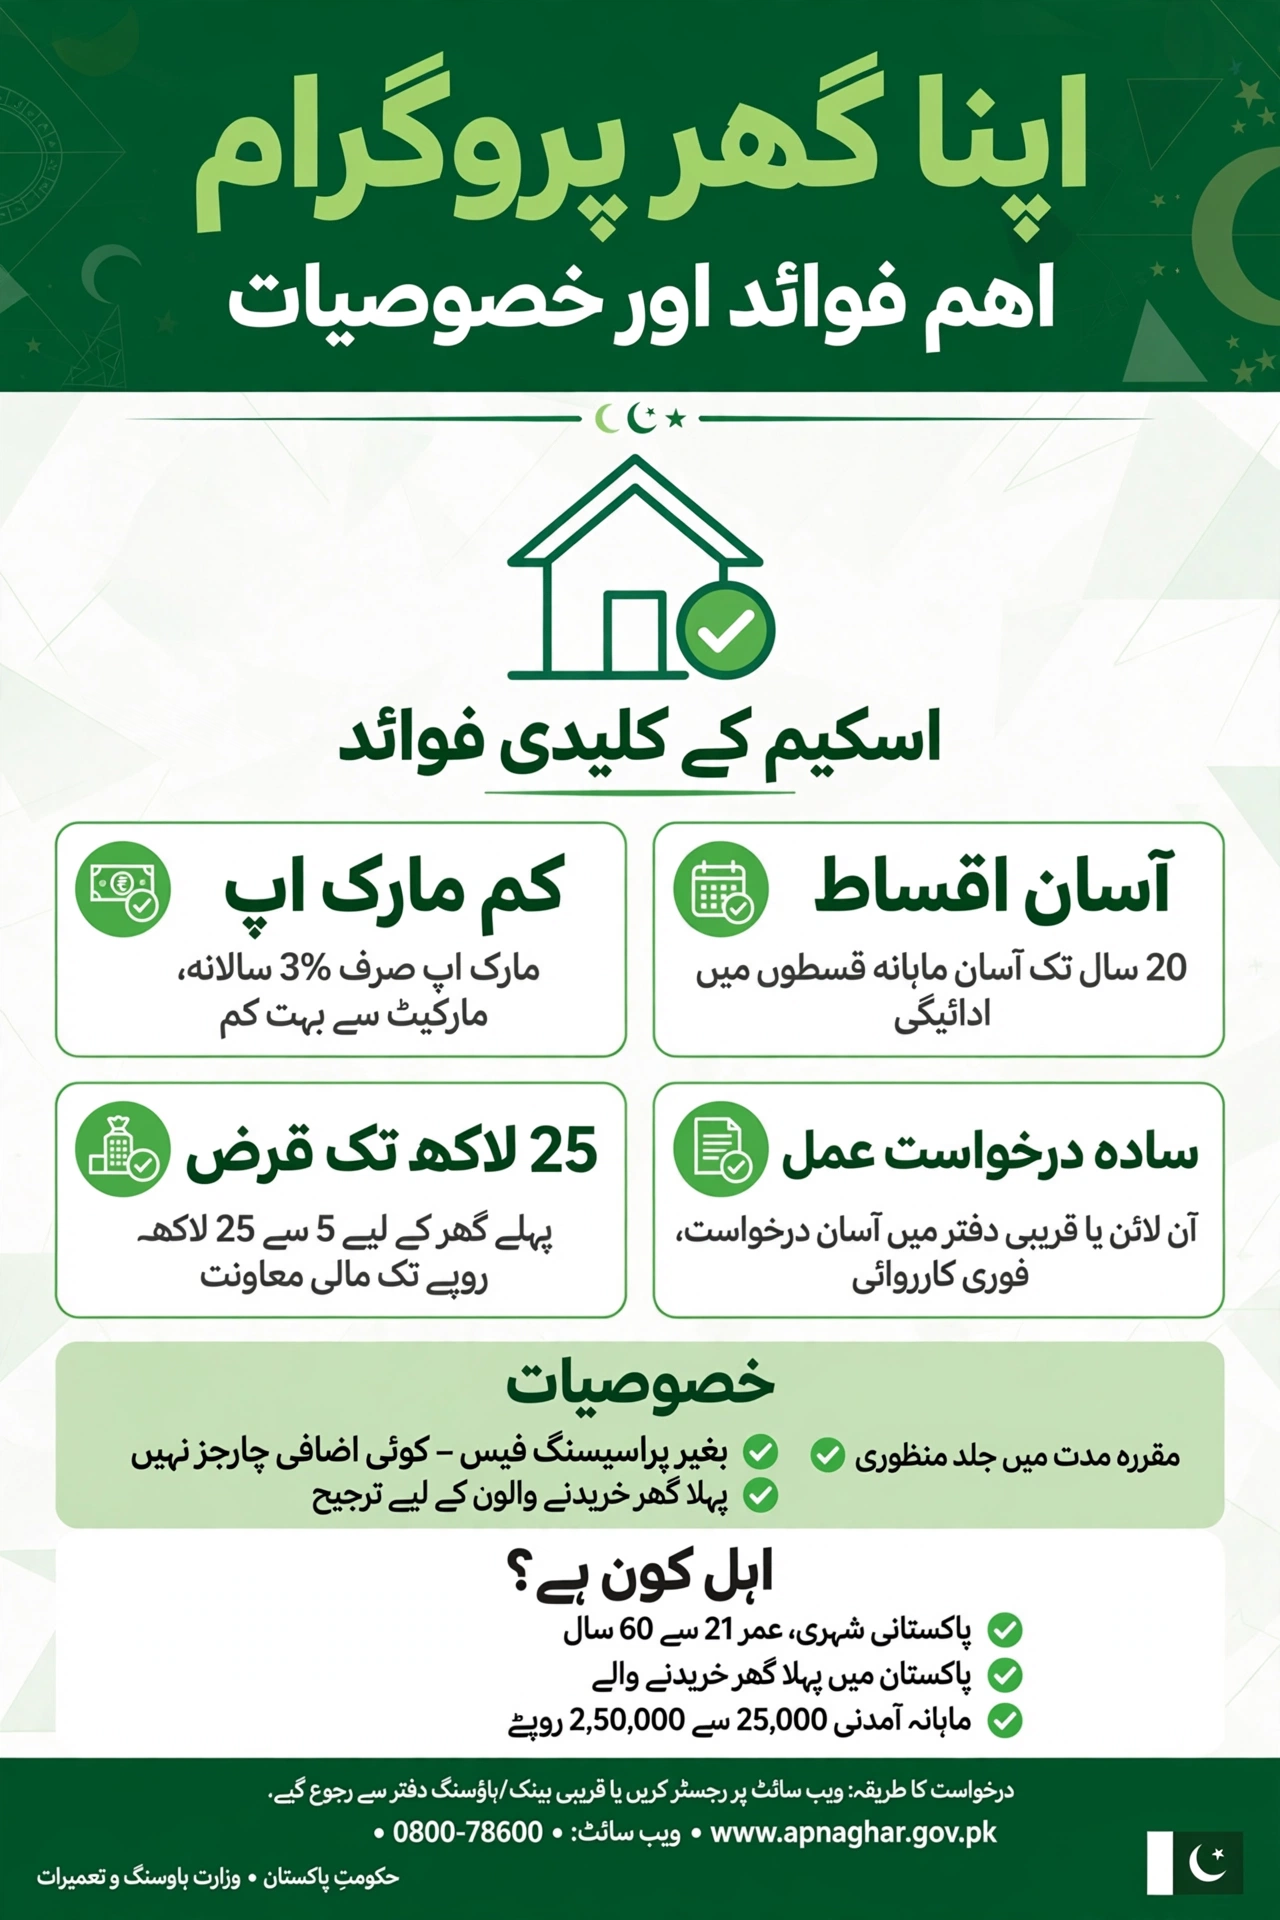
Apna Ghar Program Benefits at a Glance
| Benefit | What You Get |
|---|---|
| Subsidized markup | Fixed 5% per annum for the first 10 years |
| Low down payment | Only ~10% of the property value from your pocket |
| Long tenure | Up to 20 years — keeps monthly installments affordable |
| High financing amount | Up to Rs. 10 million |
| No processing fee | Zero upfront bank processing charges |
| No prepayment penalty | Repay early without extra cost |
| Islamic options | Shariah-compliant financing available (e.g., Meezan Bank) |
Subsidized Markup Rate
The headline benefit: instead of commercial mortgage rates of 20%+, eligible applicants pay a fixed 5% markup for the first 10 years. On a Rs. 5 million loan, that difference saves you lakhs over the loan’s life. See the full markup rate guide.
Low Down Payment
The program finances up to 90% of the property’s value — you need only about 10% as a down payment. For a Rs. 5 million house, that’s roughly Rs. 500,000 instead of the millions conventional banks demand.
Long Repayment Tenure
With up to 20 years to repay, monthly installments stay within reach of middle-income salaries. Your age determines the maximum tenure — see the age limit guide.
Who Benefits Most?
- First-time homeowners: the program is designed for you — priority access and the best terms.
- Salaried middle-class families: stable income + subsidized markup = affordable installments.
- Young earners: apply early for the longest tenure and lightest monthly burden.
- Overseas Pakistanis: invest in a home back home with official, transparent financing.
- Plot owners: build on your own land with staged construction financing.
Benefits vs Conventional Home Loans
| Feature | Apna Ghar Program | Conventional Mortgage |
|---|---|---|
| Markup rate | Fixed 5% (first 10 years) | 20%+ (variable) |
| Down payment | ~10% | 20–30% |
| Processing fee | None | Usually charged |
| Prepayment penalty | None | Often charged |
| Max tenure | 20 years | 15–20 years |
The difference is clear — but remember the program has strict rules and conditions in return.
FAQs – Apna Ghar Program Benefits
What is the biggest benefit of the Apna Ghar Program?
The fixed 5% markup for the first 10 years — far below conventional mortgage rates, saving borrowers lakhs.
How much down payment do I need?
Only about 10% of the property’s valued price, since the program finances up to 90%.
Is there any processing fee?
No — the program charges no processing fee.
Can I repay the loan early?
Yes — there is no prepayment penalty, so early repayment costs you nothing extra.
Are Islamic financing options available?
Yes — participating Islamic banks like Meezan Bank offer Shariah-compliant structures under the program.
Do the benefits apply to flats as well?
Yes — houses, flats, plot construction, and renovation all get the same subsidized terms.
What’s the catch?
The subsidized terms come with strict eligibility, property, and usage rules — read the rules and conditions guide before applying.
Final Thoughts
The Apna Ghar Program benefits — 5% fixed markup, 10% down payment, 20-year tenure, zero fees — make it the most accessible route to home ownership Pakistan has offered in years. If you meet the eligibility criteria, this is the opportunity to turn rent into ownership. Questions? The helpline guide has you covered.