Millions of Pakistanis working abroad dream of owning a home back in Pakistan — and the Apna Ghar Program for overseas Pakistanis makes that dream achievable. Under the Wazir-e-Azam Apna Ghar Program 2026, overseas Pakistanis holding NICOP or POC can apply for subsidized housing finance from abroad, with the same benefits as local applicants: 5% fixed markup for 10 years, up to 90% financing, and up to 20-year tenure. In this complete guide, we explain the eligibility rules, required documents, how to apply from abroad, loan terms, repayment options, and answers to the most common questions.
Can Overseas Pakistanis Apply for Apna Ghar Program?
Yes. The program accepts NICOP (National Identity Card for Overseas Pakistanis) and POC (Pakistan Origin Card) holders in specific cases, which means overseas Pakistanis are not excluded from the scheme. The key conditions are the same as for local applicants — you must be a first-time home buyer and meet the income and documentation requirements. Because individual banks apply their own policies on top of the federal framework, always confirm the exact overseas-applicant rules with your chosen bank from the list of participating banks.
Eligibility Criteria for Overseas Pakistanis
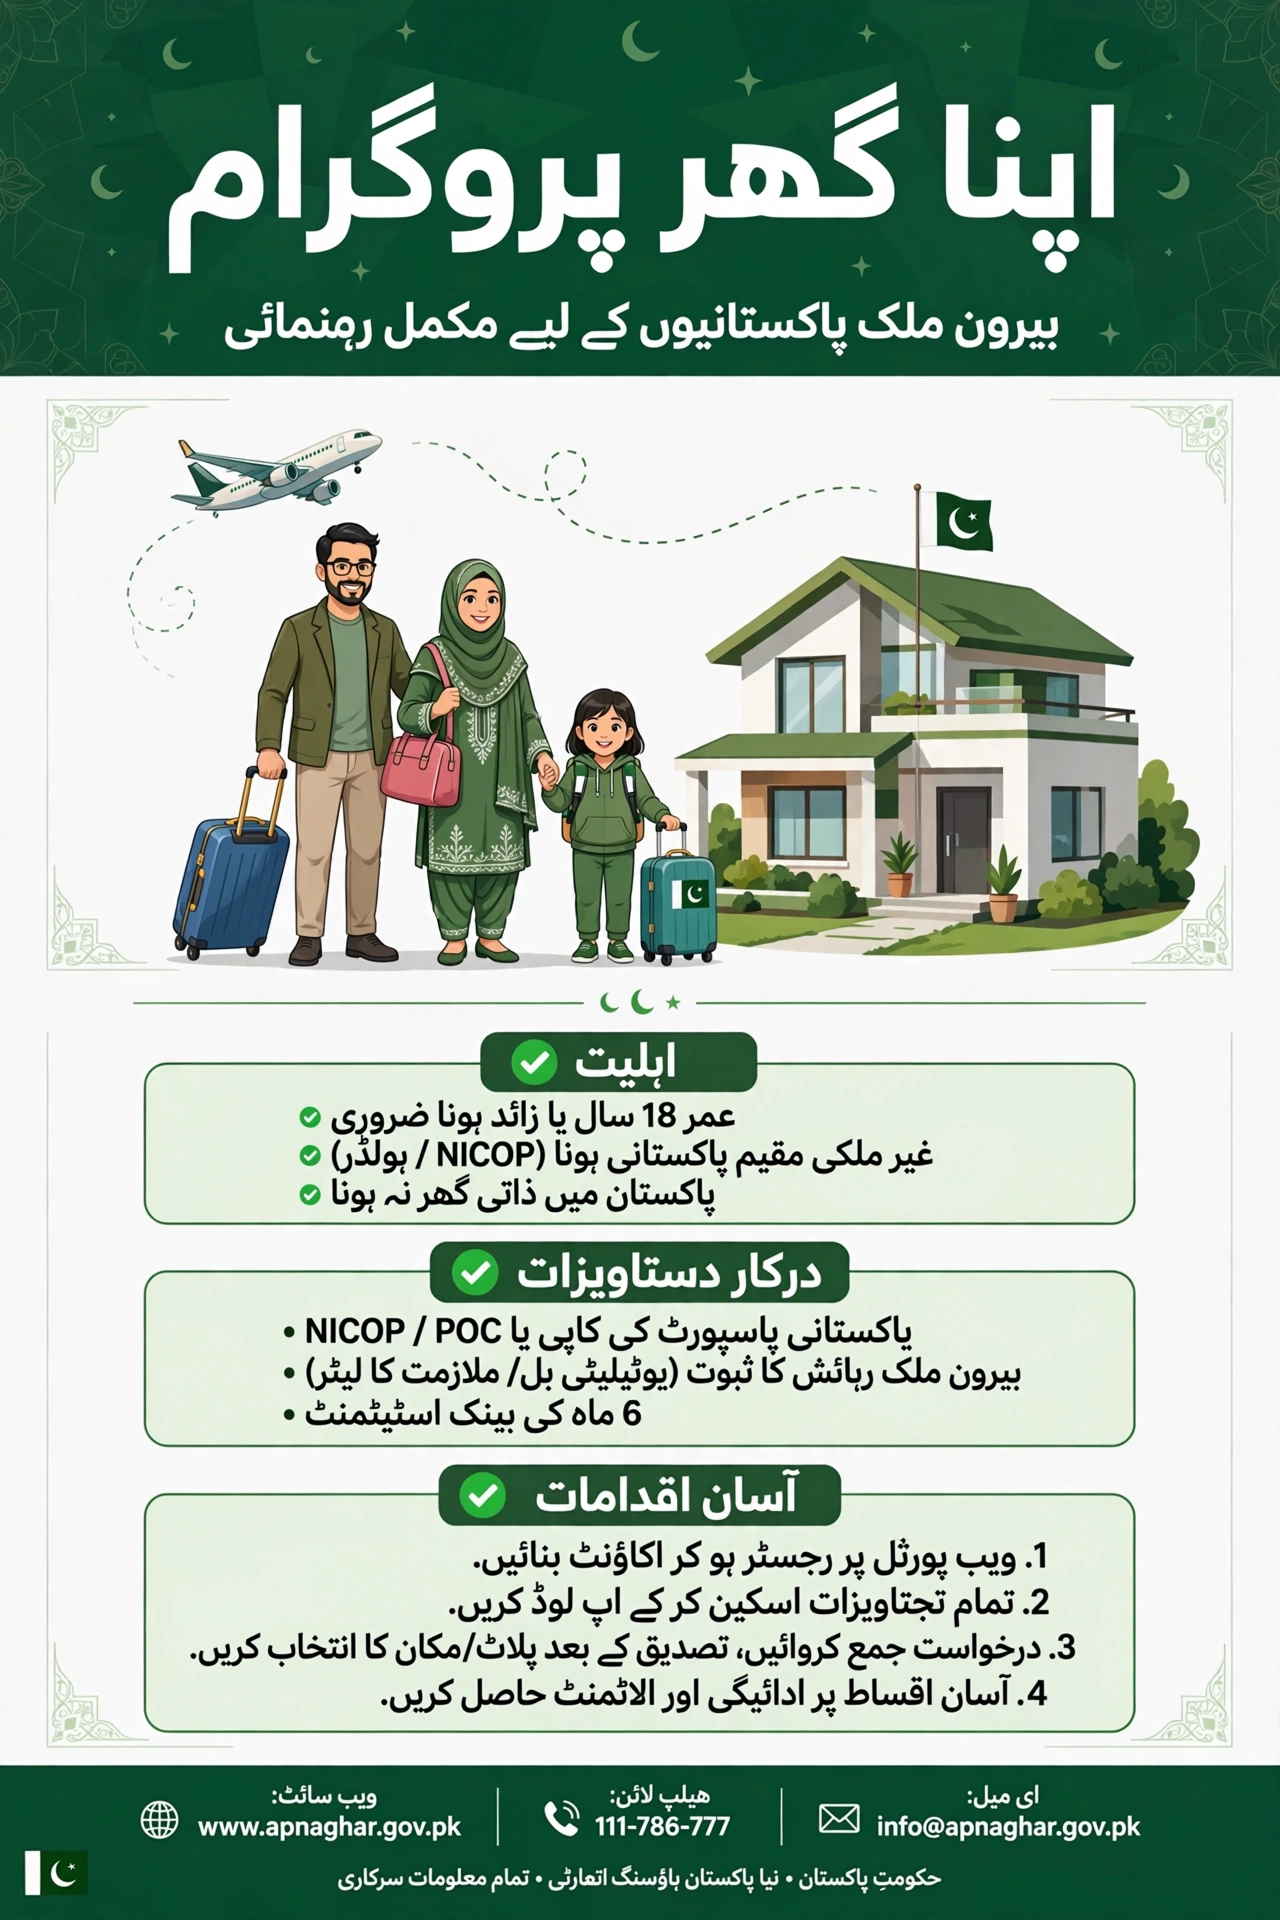
- Pakistani origin with a valid NICOP or POC (in place of a standard CNIC).
- First-time home buyer — you, your spouse, or dependents should not already own a residential property in Pakistan.
- Age up to 60 years for salaried applicants and 65 years for self-employed applicants at the time the loan matures.
- Verifiable foreign income — generally equivalent to the local minimum threshold of around Rs. 25,000–35,000 per month, though banks assess overseas income in foreign currency.
- At least 2 years of overseas employment, or 3 years of verifiable business or professional income for self-employed applicants.
Read the standard conditions in our eligibility criteria guide.
Documents Required for Overseas Applicants
- Valid NICOP or POC (front and back scanned copies)
- Pakistani passport copy
- Proof of overseas employment — work permit, employment contract, or employer letter
- Proof of foreign residence — utility bill or residence permit
- Foreign income proof — salary slips or tax documents from the host country
- Bank statements (usually the last 6 months, including remittance records)
- Property documents — depending on whether you choose house purchase or plot construction
- Recent passport-size photographs
Documents issued abroad may need attestation — check with your bank whether embassy attestation or an apostille is required. Our documents verification guide covers the general paperwork rules.
How Overseas Pakistanis Can Apply from Abroad
The entire process can be completed without visiting Pakistan:
Step 1: Confirm Your Eligibility
Verify the eligibility criteria and confirm with your bank that it accepts overseas applicants.
Step 2: Prepare and Attest Your Documents
Scan all documents clearly and get foreign-issued papers attested as required by your bank.
Step 3: Register on the Official Portal
Create your account on the Apna Ghar Program portal using your NICOP details and an email address you actively use. Our registration guide walks you through it.
Step 4: Fill the Application Form
Complete the application form carefully — enter your foreign address, employer details, and income in the correct sections.
Step 5: Choose Your Bank and Financing Purpose
Select a participating bank and choose between house purchase, plot construction, or plot plus construction.
Step 6: Verification and Property Inspection
The bank verifies your documents and income (sometimes through its overseas correspondent arrangements) and inspects the property in Pakistan.
Step 7: Approval and Disbursement
On approval, funds are disbursed and the property is registered. Track every stage with our application tracking guide.
Loan Terms for Overseas Pakistanis
Overseas applicants get the same subsidized terms as local applicants:
| Feature | Detail |
|---|---|
| Maximum loan | Up to Rs. 10 million (based on property value and repayment capacity) |
| Markup rate | Fixed 5% per annum for the first 10 years; then 1-year KIBOR + 3% |
| Loan tenure | Up to 20 years |
| Financing ratio | Bank finances up to 90%; 10% down payment |
| Processing fee | Zero processing fees and no prepayment penalty |
Learn how the rate works in our markup rate guide.
How to Manage Repayment from Abroad
- Set up a Pakistani bank account (many banks allow overseas Pakistanis to open and operate accounts remotely) and arrange automatic monthly transfers.
- Always send installments through official banking channels so every payment is documented — this protects your credit record.
- Keep a 2–3 month payment buffer in your Pakistani account to cover exchange-rate swings or transfer delays.
- Inform your bank immediately if you change jobs or countries, so your income records stay current.
Common Challenges and How to Overcome Them
| Challenge | Solution |
|---|---|
| Document attestation from abroad | Use your nearest Pakistani embassy or consulate; ask your bank exactly which attestations it needs |
| Verifying a property without visiting | Appoint a trusted family member with a registered power of attorney, or use the bank’s own valuation |
| Income in foreign currency | Banks convert using prevailing rates; provide official salary slips and tax documents |
| Communication delays | Use your registered email and the portal’s tracking system instead of relying on phone calls |
FAQs – Apna Ghar Program for Overseas Pakistanis
Can I apply with NICOP instead of CNIC?
Yes — NICOP and POC holders are accepted in specific cases. Confirm the exact requirement with your chosen bank before applying.
Do I need to visit Pakistan to apply?
No. Registration, form submission, and document uploads are all online. Property inspection and registration in Pakistan can be handled through your bank and an authorized representative.
Is the markup rate the same for overseas Pakistanis?
Yes — the same subsidized structure applies: 5% fixed for 10 years, then 1-year KIBOR + 3%.
How do I pay monthly installments from abroad?
Through official bank transfers into your Pakistani account, ideally automated. Keep payment records for every installment.
Can my family member in Pakistan apply on my behalf?
Usually a registered power of attorney is needed for someone to act for you in property matters. The loan application itself should be in your name with your NICOP.
What if I lose my overseas job during the loan tenure?
Inform your bank immediately. With no prepayment penalty, options like partial prepayment or restructuring can be discussed before you miss payments.
Can overseas Pakistanis choose Islamic financing?
Yes — participating Islamic banks offer Shariah-compliant structures with an equivalent subsidized profit rate.
Final Thoughts
The Apna Ghar Program for overseas Pakistanis puts homeownership in Pakistan within reach without requiring you to fly home for paperwork. The formula for success is simple: a valid NICOP or POC, properly attested documents, honest income reporting, and a bank that clearly accepts overseas applicants. Start with the online registration, and your family in Pakistan could soon be holding the keys to your own home.