If you want to buy a ready-built house instead of constructing one, Apna Ghar Program house purchase financing is the simplest option under the Wazir-e-Azam Apna Ghar Program 2026. Eligible Pakistanis can get a subsidized home loan to purchase a complete house or apartment — with a fixed 5% markup for the first 10 years, up to 90% financing, and repayment spread over up to 20 years. In this complete guide, we explain the eligibility criteria, property requirements, loan terms, required documents, step-by-step purchase process, and answers to the most common questions.
What Is Apna Ghar Program House Purchase?
House purchase is one of the three financing purposes covered under the Apna Ghar Program, alongside constructing on your own plot and buying a plot plus construction. With this option, the bank finances the purchase of a ready-built residential property — a house or apartment that is complete and ready to move into. Unlike construction financing, the full approved loan amount is disbursed at the time of purchase, directly facilitating the transfer of the property into your name. Learn more about the overall scheme in our Apna Ghar Program loan guide.
Eligibility Criteria for House Purchase
To qualify for house purchase financing, you must meet the program’s standard eligibility conditions:
- Pakistani citizen holding a valid CNIC (NICOP/POC accepted for overseas Pakistanis in specific cases).
- First-time home buyer — you, your spouse, or dependents should not already own a residential property.
- Age up to 60 years for salaried applicants and 65 years for self-employed applicants at the time the loan matures.
- Minimum monthly income generally starting around Rs. 25,000–35,000 (a co-applicant such as a spouse can be added to strengthen the application).
- At least 2 years of salaried employment, or 3 years of verifiable business or professional income for self-employed applicants.
Read the full details in our Apna Ghar Program eligibility criteria guide.
Property Requirements for a Ready-Built House
The house or apartment you want to buy must meet these conditions:
- Size limits: houses up to 10 Marla (about 2,720 sq. ft.), or apartments/flats up to 1,500 sq. ft. covered area.
- Clear title: the seller must have complete, verifiable ownership documents — registry, fard-e-malkiat, or intiqal — with no disputes or stay orders.
- Residential property: the property must be residential and located in an approved housing society or within municipal/town committee limits.
- Valuation: the bank will get the property independently valued; the loan is based on the lower of the agreed price and the bank’s valuation.
- No major legal issues: properties under litigation, with unpaid dues, or built in violation of approved maps are not accepted.
How to Buy a House Under Apna Ghar Program
Follow these seven steps:
Step 1: Confirm Your Eligibility
Check the eligibility criteria and estimate your affordable price range using your income and the 90:10 financing model.
Step 2: Find a Suitable House
Shortlist ready-built houses or apartments within the program’s size limits and your budget, in approved societies or municipal areas.
Step 3: Verify the Property Documents
Before committing, verify the seller’s ownership documents, check for disputes, and confirm there are no unpaid utility bills or society dues.
Step 4: Register on the Official Portal
Create your account and fill in the online application form, selecting the house purchase option. Our step-by-step registration guide walks you through it.
Step 5: Choose Your Bank and Submit
Select a participating bank from the list of Apna Ghar Program banks in Pakistan and submit the application with the property details and your documents.
Step 6: Bank Valuation and Verification
The bank verifies your documents and income, values the property through an approved evaluator, and confirms the legal status of the title.
Step 7: Approval, Disbursement and Transfer
Once approved, the loan is disbursed and the property is legally transferred into your name. Track your case with our application tracking guide.
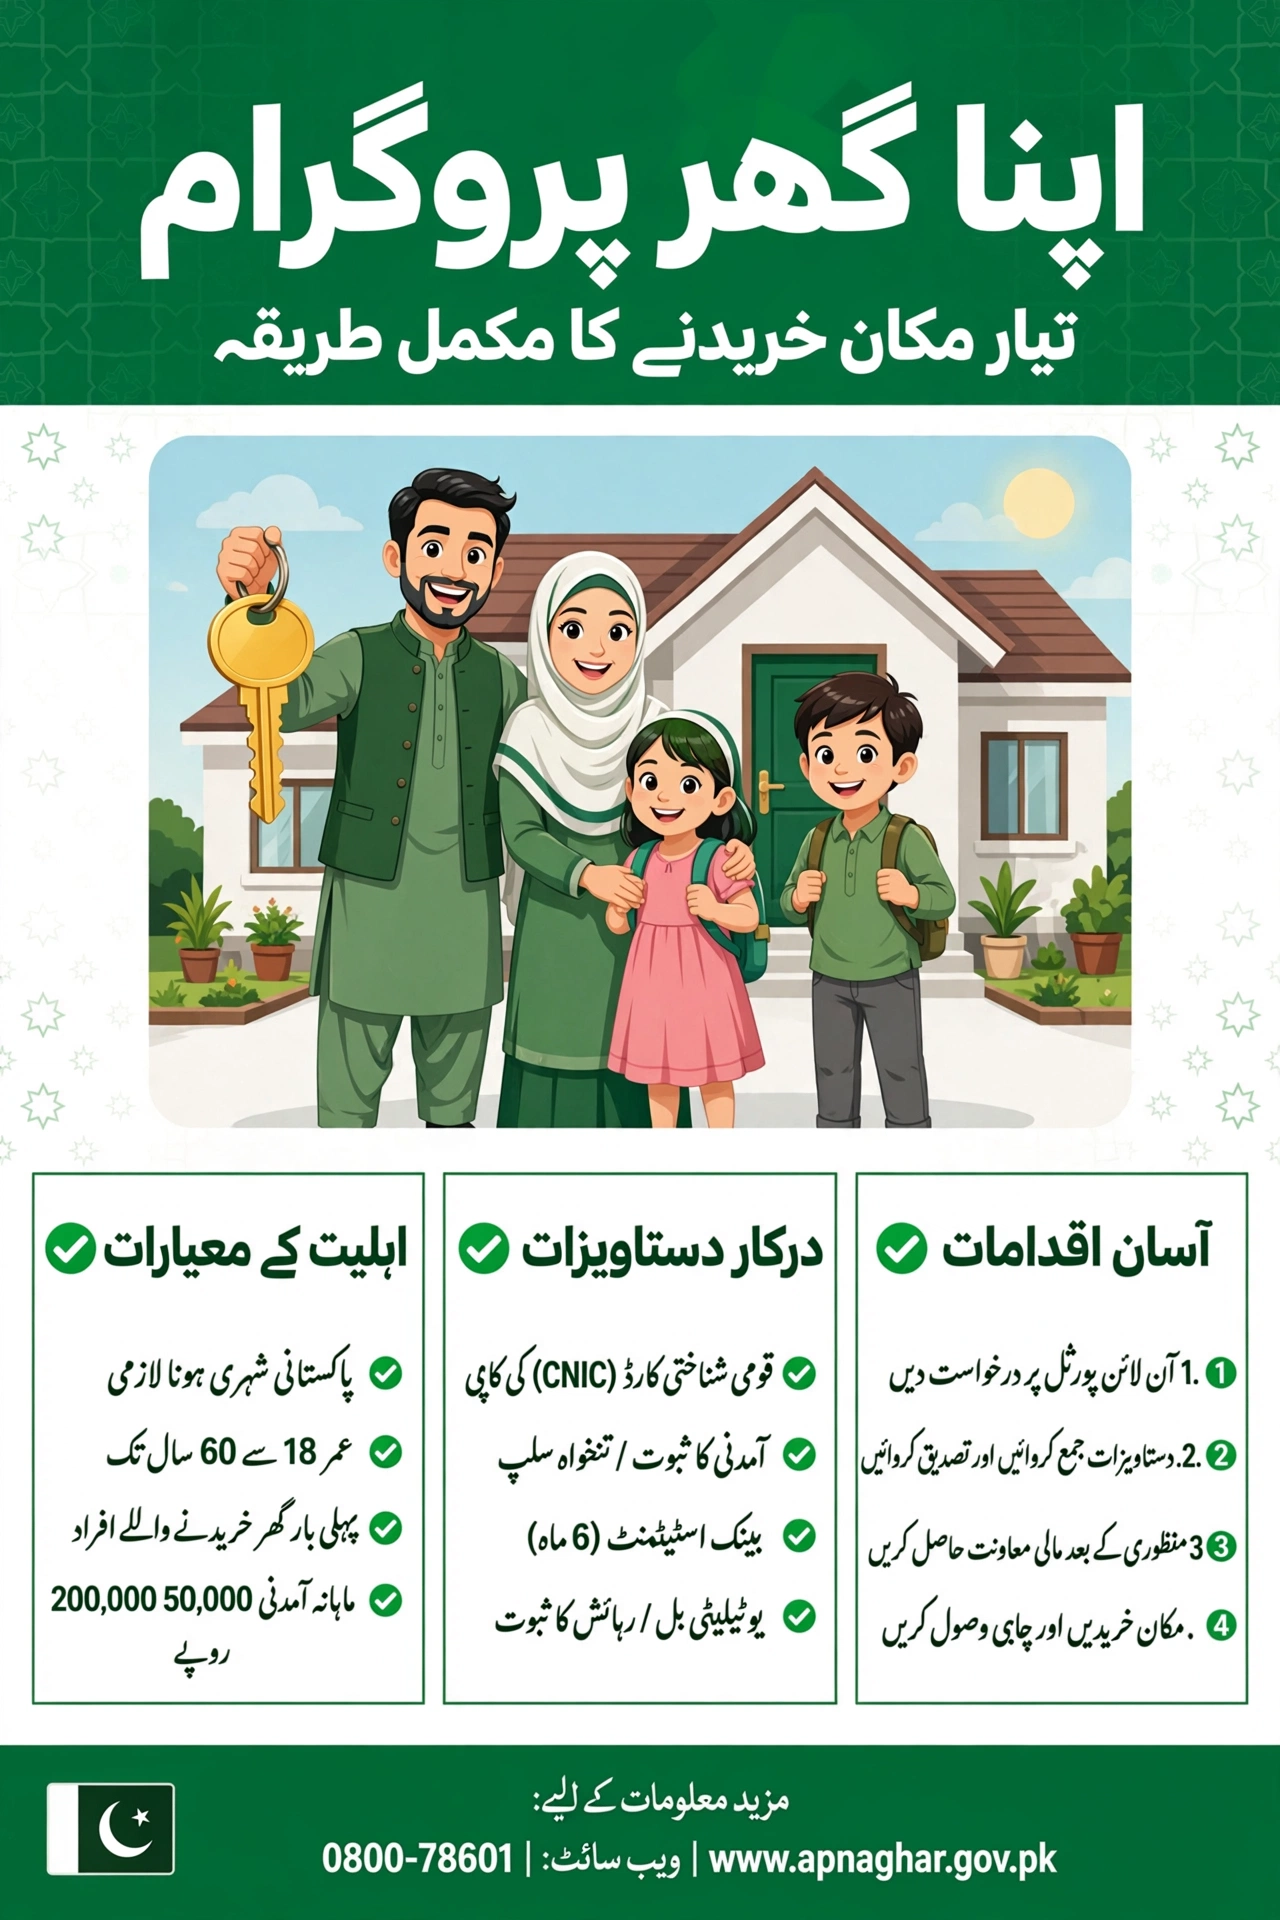
Documents Required for House Purchase
- Copy of valid CNIC (applicant and co-applicant, if any)
- Income proof — salary slips or business income evidence
- Bank statements (usually the last 6 months)
- Seller’s ownership documents — registry, fard-e-malkiat, or intiqal
- Approved map of the property (where applicable)
- Sale agreement (bayana) between buyer and seller
- Utility bills and proof of no outstanding dues
- Recent passport-size photographs
See our documents verification guide to avoid the most common paperwork mistakes.
Loan Amount, Markup and Repayment Terms
| Feature | Detail |
|---|---|
| Maximum loan | Up to Rs. 10 million (based on property value and repayment capacity) |
| Markup rate | Fixed subsidized 5% per annum for the first 10 years; then 1-year KIBOR + 3% |
| Loan tenure | Up to 20 years |
| Financing ratio | Bank finances up to 90%; you arrange 10% as down payment |
| Processing fee | Zero processing fees and no prepayment penalty |
| Sample installment | Around Rs. 2.5 million loan carries a monthly installment starting at approximately Rs. 16,499 |
House Purchase vs Plot Construction – Which Is Better?
| Factor | House Purchase | Plot Construction |
|---|---|---|
| Move-in time | Immediate after transfer | 6–18 months of construction |
| Disbursement | Full amount at purchase | Stage-wise as work progresses |
| Best for | Those without a plot | Those who already own a plot |
| Price control | Fixed agreed price | Construction cost can vary |
If you already own land, read our plot construction guide; for building tips, see the house construction guide.
Common Mistakes That Delay Approval
- Choosing a property with a disputed or unclear title.
- Agreeing on a price far above the bank’s valuation — the loan follows the valuation, not your deal.
- Paying a large advance (bayana) before the bank approves the property.
- Ignoring unpaid utility bills or society dues attached to the property.
- Submitting incomplete income proof.
Many of these issues are also covered in our rejection reasons guide — read it before you apply.
FAQs – Apna Ghar Program House Purchase
Can I buy a house in any city under this program?
Yes, as long as the property is residential, within the size limits, and located in an approved housing society or municipal area with verifiable title documents.
What is the maximum loan for house purchase?
Up to Rs. 10 million, based on the property’s value (or the bank’s valuation, whichever is lower) and your repayment capacity. The bank finances up to 90% of the price.
Is the house purchase loan interest-free?
It is subsidized, not interest-free: a fixed 5% per annum markup applies for the first 10 years, switching to 1-year KIBOR + 3% afterwards.
How much down payment do I need?
You need to arrange 10% of the property price as your own equity; the bank finances the remaining 90%.
Can I buy an apartment or flat instead of a house?
Yes — apartments and flats up to 1,500 sq. ft. covered area are covered under the program.
How long does approval take?
Timelines vary by bank, but complete applications with verified property documents are typically processed within a few weeks. Track your status with our tracking guide.
Can the seller be a relative?
Banks scrutinize related-party transactions closely to prevent misuse. Such cases usually require extra documentation and valuation checks — discuss it with your bank before applying.
Final Thoughts
Apna Ghar Program house purchase is the fastest way to own your home under the scheme: no construction wait, a fixed purchase price, and subsidized financing with up to 20-year tenure. The keys to smooth approval are a dispute-free property title, a realistic price aligned with bank valuation, and complete documents. Start with the online registration, verify the property carefully, and you could be holding your own house keys within weeks.